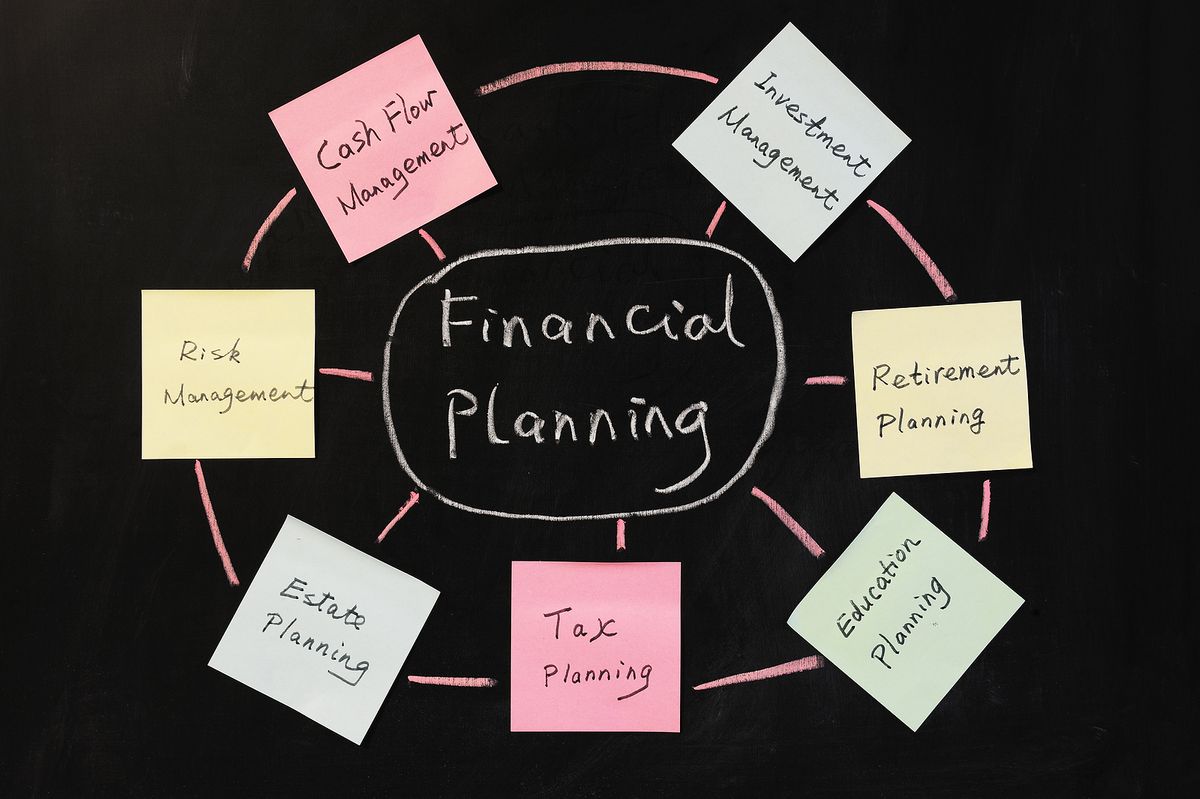
Financial planning is unique to each person, since every household has different goals, income, and priorities. A plan can also help you stay on track or make changes as life evolves.
The first step in planning is to examine one’s current financial situation by assessing budget, debt management, savings, retirement planning, insurance, and estate planning. Building a first plan can take more time, since factors such as marital status, assets, income, health, employee benefits, children, and future retirement income all shape the plan.
A plan can’t guarantee protection from unexpected life events, but it can provide a blueprint. Every plan begins by first addressing these eight things:
1. Build an Emergency Fund
An emergency fund is money set aside for unexpected expenses, such as a job loss, car repair, or medical bill. Many people aim for three to six months of living expenses in an accessible account.
2. Create a Monthly Budget
A budget estimates monthly income and expenses, showing where money goes and where adjustments may free up cash for other goals.
3. Make a Debt Reduction Plan
A debt reduction plan prioritizes balances, often starting with high-interest debt such as credit cards. Paying down debt may reduce financial stress and free up cash flow.
4. Save Consistently
Regular saving, even in small amounts, can help fund near- and long-term goals. Automatic transfers can make saving more consistent.
5. Improve one’s tax situation
A plan can outline tax-advantaged strategies, such as contributing to tax-deferred retirement accounts or a health savings account (HSA), that may help reduce your overall tax bill.
6. Save for Retirement
The retirement component of a plan often includes projections based on assumed rates of return, which can help you see whether you're on track or need to adjust. Projections are hypothetical, are not guarantees, and actual results will vary.
7. Save For Education
Including education savings in a plan can help estimate how much to save for a funding goal. A 529 plan offers tax-free growth when withdrawals are used for qualified education expenses. Arizona taxpayers may deduct contributions to any state's 529 plan, up to $2,000 per year for single filers or $4,000 for married couples filing jointly. Earnings on nonqualified withdrawals are subject to income tax and a 10% federal penalty.
8. Save for Other Goals
Whether the goal is a home, travel, or a new business, a plan can help you work toward the funds to reach it.
How a Financial Professional Can Help
An experienced financial professional can help guide you through the financial planning process by providing guidance in several areas of your financial life. A financial professional can help you:
· Determine whether you're on track to meet your goals
· Get a second opinion on your current plan
· Evaluate your portfolio's investment strategy and consider changes
· Assess your risk tolerance and time horizon to align with your goals
· Prepare for setbacks that can affect your finances, such as job loss or divorce
Financial Planning FAQs
How much should I keep in an emergency fund?
Many people aim for three to six months of living expenses, though the right amount depends on job stability, income sources, and household needs.
Does Arizona offer a tax deduction for 529 contributions?
Yes. Arizona taxpayers may deduct contributions to any state's 529 plan, up to $2,000 per year for single filers or $4,000 for married couples filing jointly. A tax professional can confirm how it applies to you.
Take the next step and schedule a planning meeting with a financial professional today to start putting your plan into action.