Blog
Keep up to date with our news, tips & tricks, and latest information!
Mid-Term Elections and Your Portfolio
Jeff Martin, CRPC®
Elections bring uncertainty, and markets often react to uncertainty. Midterm elections, held every four years between presidential elections, can influence investor sentiment and short-term market movements. Here are several ways a midterm election may affect your portfolio, and why a long-term perspective matters.
1. Market Volatility
Markets have at times experienced heightened volatility in the months leading up to elections, as investors weigh possible policy changes. Some investors react by making sudden changes to their portfolios, which can work against long-term goals. Past market patterns around elections may not repeat.
2. Sector Sensitivity
Policy agendas can affect some industries more than others, including energy, healthcare, financial services, and defense. Markets often price in expectations before an election, so sector moves can be difficult to anticipate, and elections are only one of many factors affecting any industry.
3. Investor Sentiment
Investor confidence can shift during an election season, sometimes based on headlines rather than economic fundamentals. Sentiment-driven moves may be short-lived.
more
Investing in AI: Is the Risk Worth the Reward?
Jeff Martin, CRPC®
Artificial intelligence (AI) has drawn significant attention in the investment world. Many investors are interested because AI is being applied across a wide range of industries, from healthcare and education to finance and entertainment. But potential opportunity comes with meaningful risk, and understanding both sides is essential before investing.
Why Investors Are Drawn to AI
AI isn't limited to startups or technology companies. Businesses in manufacturing, retail, healthcare, and transportation are also developing and using AI. Here in the Phoenix area, semiconductor manufacturing, a key part of the AI supply chain, has become a significant part of the local economy.
Because AI-related companies are often viewed as high-growth opportunities, they can attract strong investor interest. That interest can also push prices higher than a company's current results support.
Key Risks of Investing in AI
· Technology risk – AI evolves quickly. Today's leading technology may be overtaken, which can hurt companies that fall behind.
· Valuation risk – Enthusiasm for AI can lead to high stock prices relative to earnings. If expectations aren't met, prices may fall sharply.
more
10 Signs an Economy is Declining
Jeff Martin, CRPC®
Understanding the health of an economy is crucial not only for economists and policymakers but also for investors. Economic downturns can have disastrous consequences, from job losses to a decline in living standards.
But how can one spot the signs of an imminent economic crash? Here are 10 potential indicators that an economy might be heading for a downturn.
1. Rising Unemployment
A rising unemployment rate often precedes a recession. It may signify that companies are facing financial difficulties and are unable to retain their workforce.
2. Inflation or Deflation
A rapid rise in the general level of prices (inflation) or a significant drop in the general level of prices (deflation) can signal economic instability.
3. Stock Market Volatility
Abrupt swings in stock prices or extended periods of low returns can indicate economic uncertainty.
4. Falling Consumer Spending
A marked decrease in consumer spending indicates reduced economic activity and can be a precursor to an economic downturn.
more
The Final Third: A Year-End Financial Refresh
Jeff Martin, CRPC®
The financial year is divided into different phases, each with its rhythm, opportunities, and challenges. But it is the final third of the year that usually attracts heightened attention. During this period, reviewing investment performance, rerouting financial resources, and making a final push toward goals should take precedence.
Why Review Your Finances Before Year-End
Reviewing financial goals during the final third of the year is strategic for several reasons:
1. To examine progress – The final third of the year is the perfect time to evaluate goal performance. By now, one should have a fair understanding of progress compared to projections.
2. To implement corrections – Evaluation provides an opportunity to make necessary changes to work toward year-end goals and plan for next year.
3. Plan charitable giving – Gifts must generally be made by December 31 to count for the current tax year, so late-year planning can help you give in a tax-efficient way.
4. Prepare for tax season – Late-year financial reviews can support tax planning and provide an opportunity to make important financial decisions that may lower one's tax liabilities.
more
Inflation Checklist: Tips to Manage Retirement Savings in Tough Times
Jeff Martin, CRPC®
How Inflation Affects Retirement Savings
The most immediate impact of inflation on retirement savings is that it erodes one's purchasing power. Over time, inflation reduces the value of money, meaning the dollar today will buy less in the future than it does now.
While inflation might seem like an abstract concept, it can have a real and tangible impact on one's retirement savings. Several practical strategies may help manage this risk as retirement savings are drawn down over time.
Inflation Checklist for Retirees
· Purchase inflation-indexed annuities - These annuities contain an inflation rider purchased at an additional cost and are designed to help protect investors from inflation. The annuity's indexed interest rate is adjusted based on changes in the inflation rate.
· Diversify the retirement savings portfolio - Investing in a mix of assets, especially those that tend to do well during inflationary periods, can help protect one's purchasing power.
· Keep a long-term growth component – Historically, stocks have outpaced inflation over long periods, though not in every period, and they carry greater short-term volatility. Past performance is not indicative of future results. A financial professional can help determine what mix is suitable for your situation.
more
How to Manage Family Wealth Across Generations
Jeff Martin, CRPC®
The "great wealth transfer" is underway. Cerulli Associates projects that $124 trillion will change hands through 2048, most of it from Baby Boomers and older generations to Generation X and Millennial heirs, as well as to charities. For families, the challenge is how to preserve that wealth and prepare the next generation to manage it.
Key Elements of a Multigenerational Wealth Strategy
Successfully transferring wealth across generations requires a comprehensive and long-term approach. There are key elements of a cross-generational wealth management strategy that families employ.
· Establishing a vision – Families must have a clear understanding of their financial goals for both the present and the future. This vision should incorporate the family's values, traditions, and ambitions. It should also provide guidance on managing wealth in the future.
· Education and communication – It’s vital that each generation understands that financial matters are vital for successful wealth management. Effective communication within the family can help them understand the shared vision and the strategies being employed to attain it.
more
What Is Liquidity, and Why Is It So Important in Retirement?
Jeff Martin, CRPC®
As individuals approach retirement, their financial situation changes, and the need for liquid assets often rises. Retirees require ready access to cash to cover anticipated expenses, unexpected costs, and other emergencies that may arise. Liquidity, meaning how quickly an asset can be turned into cash without significant loss of value, is especially important for retirees for several reasons.
Why Liquidity Matters in Retirement
Covering everyday expenses – Having cash or cash equivalents on hand can help retirees cover daily living expenses without relying on the timing of investment sales.
· Covering unexpected costs – Retirees may face expenses such as medical bills or home repairs. Liquid assets can be quickly accessed to cover these expenses, reducing the need for loans or debt.
· Flexibility – Liquidity enables retirees to adapt to changes in their financial situation or the broader economic environment. For example, if a retiree's pension or investment income decreases due to market fluctuations, they can tap into their liquid assets to cover the shortfall.
more
Why Even the Wealthy Need Long-Term Care Insurance
Jeff Martin, CRPC®
While Long-Term Care (LTC) planning is a significant concern for people across income levels, the wealthy may also have unique considerations. Even with significant assets, many choose to consider long-term care insurance (LTCI), which helps cover daily personal support and basic activities of daily living (ADLs)—such as bathing, dressing, and eating—due to chronic illness, disability, or cognitive impairment.
Why High-Net-Worth Families Consider LTC Insurance
Regardless of wealth, factors such as age, health, and potential for disability make LTC a necessity for many. While average care costs can be a small fraction of wealthy individuals' wealth, high-end care facilities, often chosen by those with significant assets, can cost much more. This is where LTCI can be beneficial.
The wealthy often hold their wealth in illiquid assets such as real estate or businesses. These assets aren't readily sold to cover care costs, which can lead to asset depletion. Despite their substantial resources, the wealthy must prepare for LTC care in their financial planning.
These individuals purchase LTCI to protect their wealth and assets for heirs or charitable organizations. This approach minimizes the financial impact of LTC, allowing them to maintain their standard of living and legacy plans.
more
Two Taxes That Can Impact Investment Returns
Jeff Martin, CRPC®
Understanding income tax and capital gains tax is crucial in financial planning. These types of taxes differ in their types, calculations, and impacts on investment returns. Here’s what investors need to know about each to make more informed decisions.
How Income Tax Works
Income tax is a direct tax imposed by governments on the financial income generated by all entities within their jurisdiction. Individuals, businesses, and corporations are obligated to pay this tax. Income tax rates are typically progressive, meaning the more one earns, the higher the tax rate. Income tax consists of:
· Ordinary income - This includes wages, salaries, commissions, and interest income. It is generally taxed at regular, progressive tax rates.
· Passive income - Income derived from rental activity, limited partnerships, or other enterprises in which the individual does not actively participate. It may be subject to the 3.8% net investment income tax (NIIT) for taxpayers with modified adjusted gross income above $200,000 (single) or $250,000 (married filing jointly).
more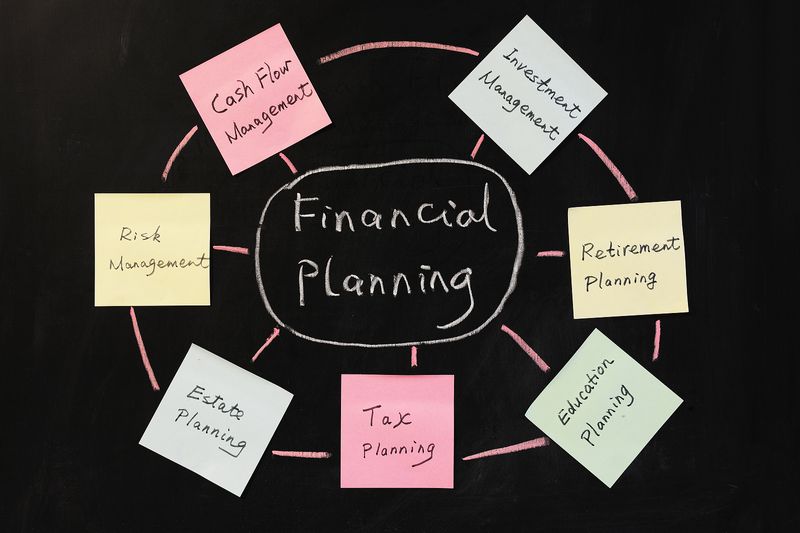
8 Things Every Financial Plan Starts With
Jeff Martin, CRPC®
Financial planning is unique to each person, since every household has different goals, income, and priorities. A plan can also help you stay on track or make changes as life evolves.
The first step in planning is to examine one’s current financial situation by assessing budget, debt management, savings, retirement planning, insurance, and estate planning. Building a first plan can take more time, since factors such as marital status, assets, income, health, employee benefits, children, and future retirement income all shape the plan.
A plan can’t guarantee protection from unexpected life events, but it can provide a blueprint. Every plan begins by first addressing these eight things:
1. Build an Emergency Fund
An emergency fund is money set aside for unexpected expenses, such as a job loss, car repair, or medical bill. Many people aim for three to six months of living expenses in an accessible account.
2. Create a Monthly Budget
A budget estimates monthly income and expenses, showing where money goes and where adjustments may free up cash for other goals.
more